A · Current refinance entry
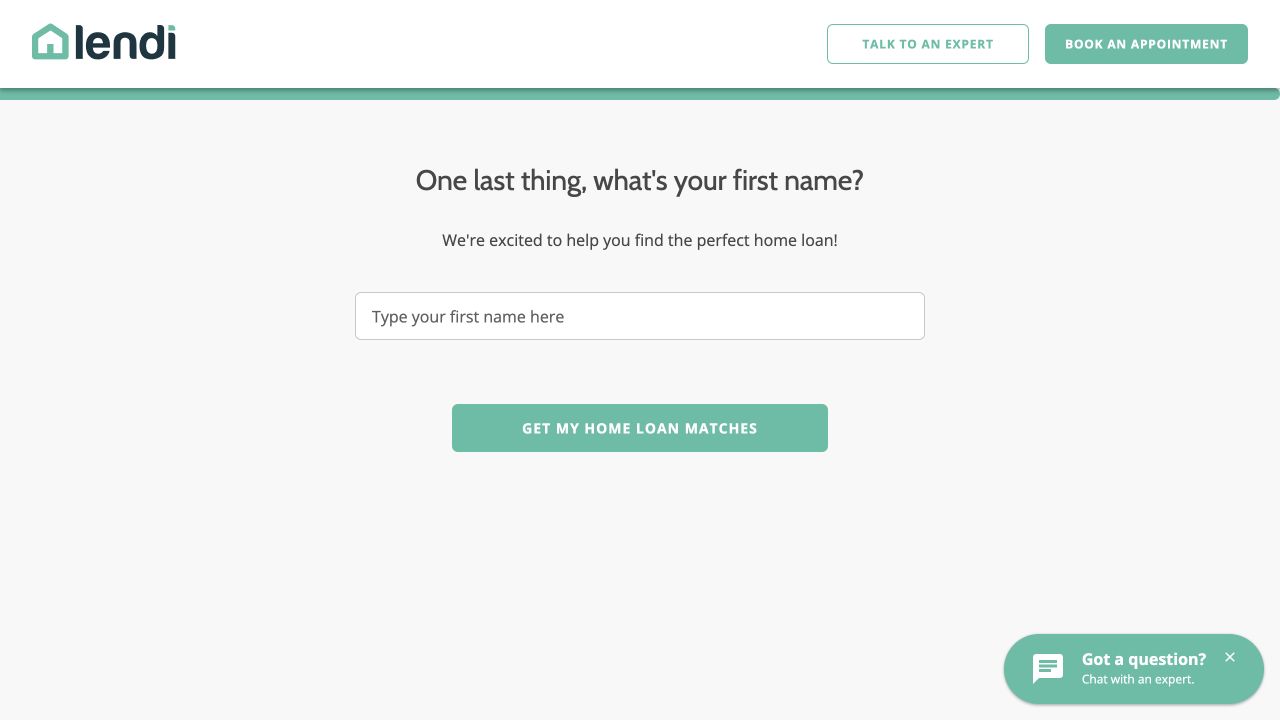
Existing landing page and comparison questionnaire. Retain its normal broker and support routes.
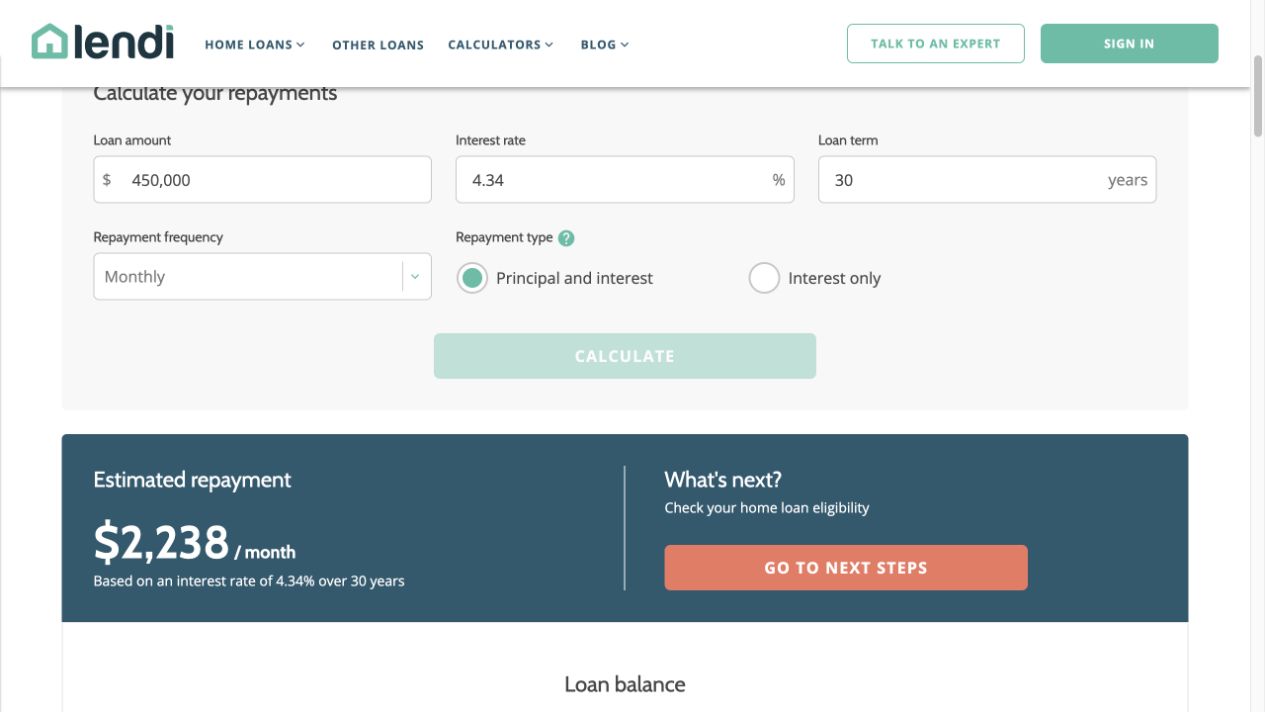
See a repayment estimate before you decide to speak with a broker.
No name, email or phone needed for an estimate.
Example inputs shown for this static concept.
Read-only example. The scenario rate is hypothetical, not a lender offer. No data is collected.
At an illustrative 6.00% rate, with the same balance and 25 years remaining:
About $225 ahead in year one after $2,000 in upfront switching costs.
Monthly principal-and-interest repayments. Both rates held constant. Upfront costs paid separately.
The costs matter. A lower rate may not make switching worthwhile if you sell or refinance again sooner.
This is a repayment scenario, not financial advice, a product comparison, an interest-saving estimate or credit approval. It excludes offset/redraw, extra repayments and ongoing fee differences. Actual switching costs may include fixed-rate break costs and LMI. Displayed amounts are rounded; differences use unrounded values.
A broker can review rates, fees, features and eligibility, and check whether switching makes sense for your circumstances.
Preview the optional broker handoffYou can use the estimate to consider a rate discussion with your current lender. The proposed tool leaves the result visible.
What to check before switchingThe customer chooses whether to share the scenario. The broker receives the inputs, assumptions and goal, then checks them.
They want to know whether the potential benefit justifies spending time on a refinance.
The inspected route asks ten sets of questions before a first-name request. No personalised result appears before it.
Our hypothesis: some suitable visitors leave before understanding the possible benefit. This is not yet measured.
Loan balance, rate and remaining term produce an estimate before identity or contact details.
The example's $185 monthly difference becomes only $225 in first-year cash-flow benefit after upfront costs.
With consent, the scenario enters the customer record as unverified information. The broker reviews and corrects it.
Borrow Angus's fast learning loop. Use random assignment and real outcomes to judge the result.
Existing landing page and comparison questionnaire. Retain its normal broker and support routes.
Repayment scenario and costs before optional contact. Preserve the surrounding page and acquisition mix.
No experiment has run. No conversion uplift or business result is claimed. Angus's referenced results were sample data, and a three-day review is not a sufficient stopping rule by itself.
Lendi already provides an ungated repayment calculator. The proposed experiment brings a useful comparison into the refinance entry.
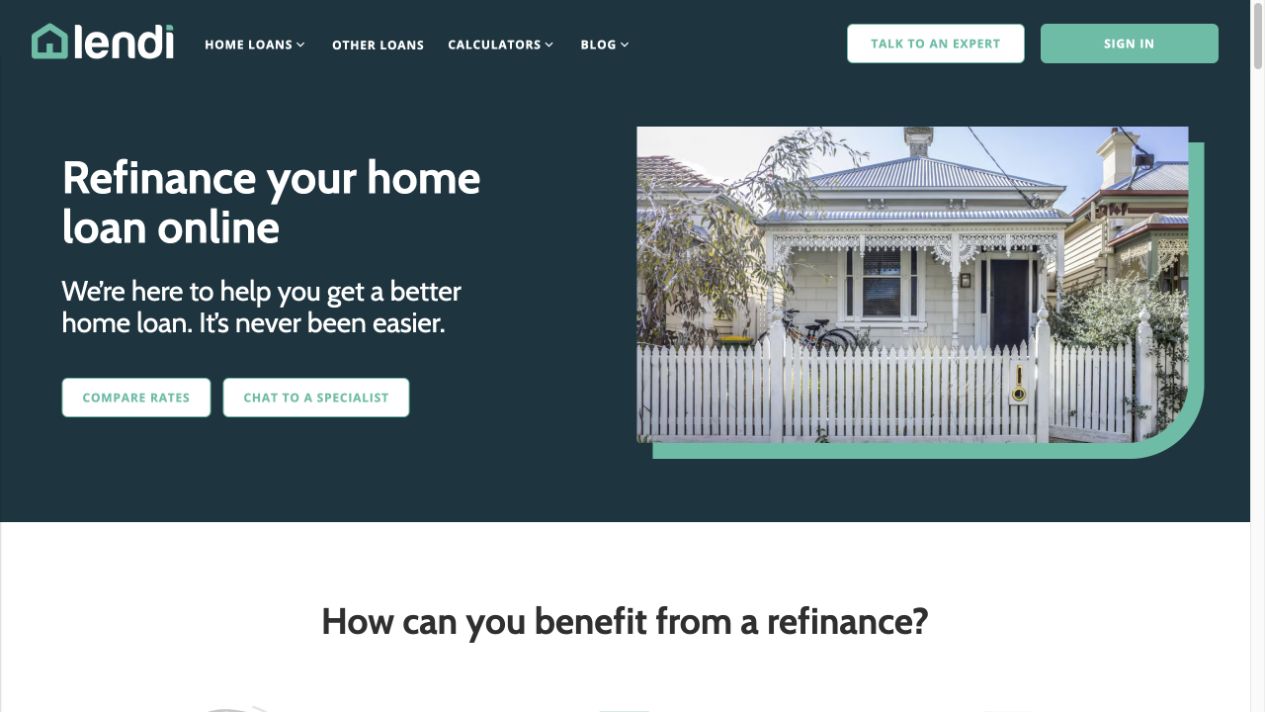
Actual public refinance page, captured 26/10/2026. This is the proposed control surface, not a reconstructed design.
Dedicated loan pages, calculators, an article library and internal links into comparison. The tested questionnaire reached a name request before a personalised result.
We do not know Lendi's drop-off, organic rankings, conversion rates or why visitors leave. The walkthrough stopped at the name request, before matches.
Search Console, conversion cohorts and borrower research would determine priority and the experiment's size.